Trailing Drawdown: Intraday vs End-of-Day Examples
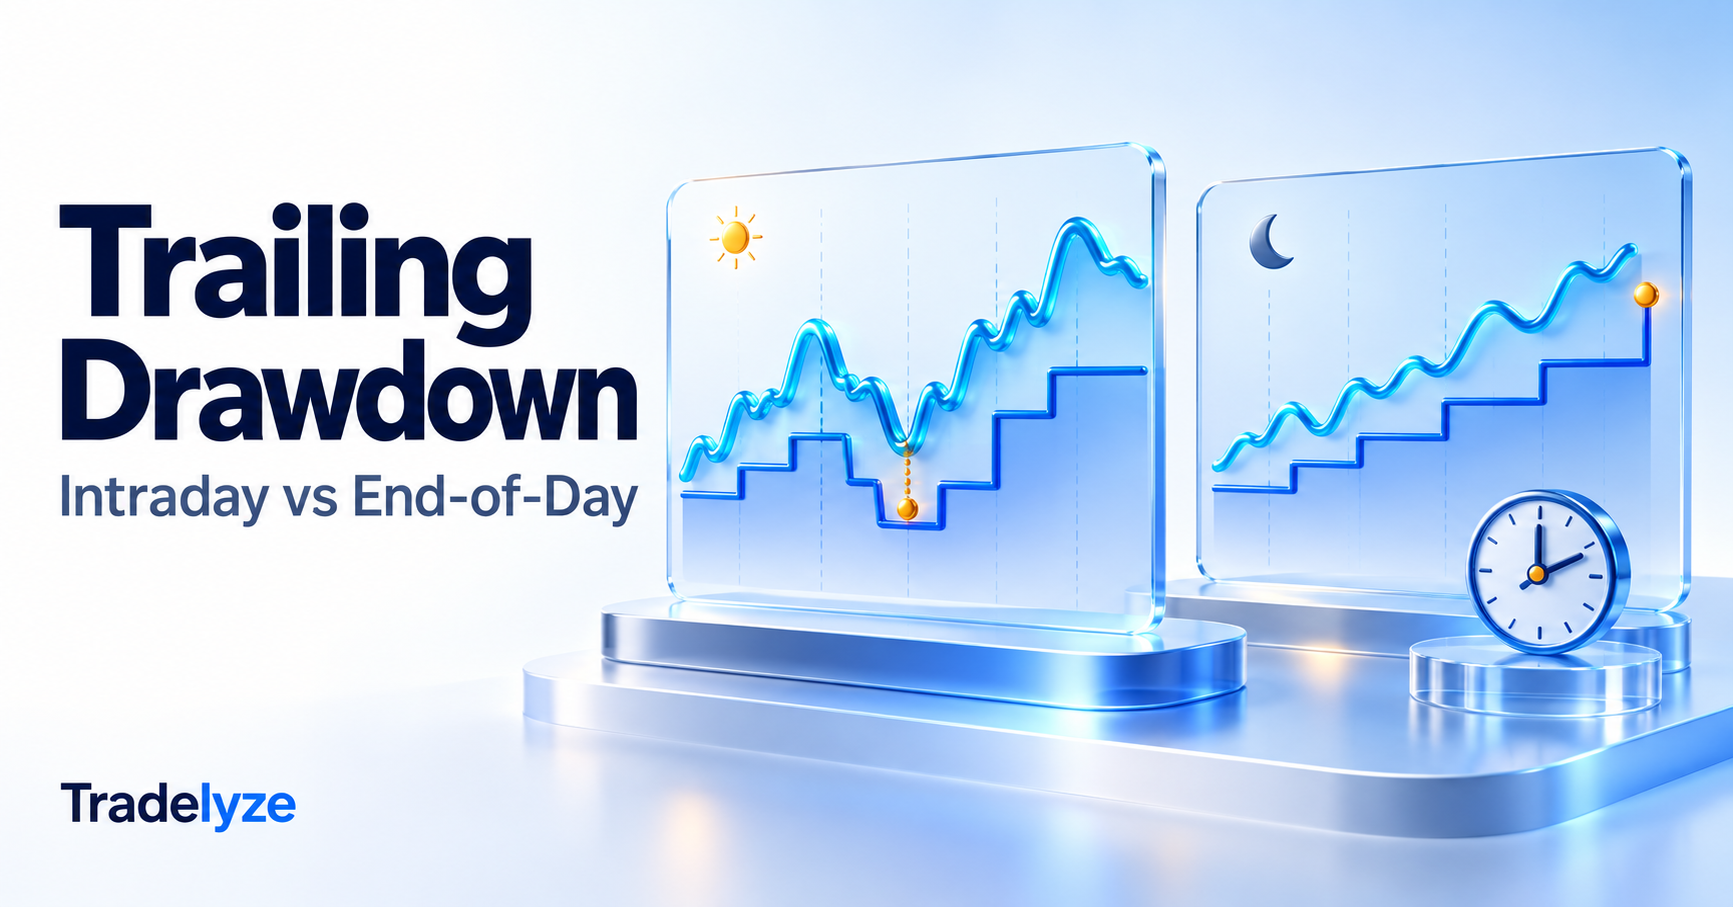
Trailing drawdown is a loss limit that moves upward as an account reaches new qualifying highs. Intraday trailing can move the floor during a trading session. End-of-day trailing moves it using qualifying closing balances. Neither name alone tells you when a breach is checked or when the floor stops rising.
Those details matter when you backtest a strategy for a prop firm. A trade can finish profitable while giving back enough open profit to violate a moving floor. An account can also break an end-of-day trailing rule before the session ends.
This guide uses worked examples to separate three questions: when does the floor update, when is it enforced, and does it eventually lock? For the broader checklist, see prop firm rules and the backtest metrics to check.
How does trailing drawdown work?
A trailing drawdown rule sets a minimum account value relative to a qualifying high. With a fixed dollar allowance, the basic calculation is the qualifying high minus that allowance. The high-water mark moves upward when the rule recognizes a new high, while the floor remains unchanged after a loss.
In a constructed account starting at $50,000 with a $1,500 allowance, the initial floor is $48,500. A qualifying high of $50,600 raises the floor to $49,100. A later fall to $50,200 doesn’t push that floor back down.
Uncapped trailing floor = highest qualifying account value − drawdown allowance.
“Qualifying” is doing important work here. The reference might be live equity, realized balance after trades close, or the highest end-of-day balance. Equity includes open-position profit or loss; realized balance does not. A percentage-based rule needs its own formula, so don’t assume every advertised percentage creates a constant dollar allowance.
Separate the floor update, enforcement and lock
Two accounts can advertise the same trailing drawdown allowance yet expose the same strategy to different rules. One may recognize every open-equity high. Another may recognize only closing balances. A third may stop trailing after reaching a stated threshold. Write those conditions separately before comparing accounts.
| Rule model | When the floor updates | When the limit is enforced | When it locks |
|---|---|---|---|
| Static floor | Set at the start; no upward trailing | As specified by the account, often including open equity | Already fixed, apart from explicit account adjustments |
| Intraday trailing | At new qualifying intraday highs; equity-based variants include open gains | As specified; our example checks continuously | Only if the terms define a lock |
| End-of-day trailing | At qualifying session closes | May still be checked throughout the next session | Only if the terms define a lock |
These are model definitions, not universal terms for every firm. Also check whether touching the floor is a violation or whether the account must fall below it. The examples below assume touching or falling below ends eligibility.
Intraday trailing drawdown example: open profit raises the floor
Under an equity-based intraday trailing rule, an open winning trade can lift the floor before you realize any profit. If that trade reverses, the floor remains at its higher level. Giving back open profit therefore uses some of the remaining loss allowance.
Assume a constructed $50,000 account, a fixed $1,500 allowance, continuous equity-based updates and enforcement, and no floor lock. All account values are net of modeled costs. The account has no other positions or adjustments.
| Moment | Account equity | Highest equity | Trailing floor | Room above floor |
|---|---|---|---|---|
| Start | $50,000 | $50,000 | $48,500 | $1,500 |
| Open trade reaches a $1,200 gain | $51,200 | $51,200 | $49,700 | $1,500 |
| Trade exits with a $600 gain | $50,600 | $51,200 | $49,700 | $900 |
| Next session: open loss of $1,000 | $49,600 | $51,200 | $49,700 | Breach: $100 below floor |
The account earned $600 on the first trade, yet began the next session with only $900 above the floor. The $600 retreat from the open-equity peak consumed part of the $1,500 allowance. Closing the winner did not restore that room.
This is why a breakeven exit doesn’t always mean a trade had no effect on account risk. If an equity-based trailing floor moved upward during the trade, the account can finish unchanged while its floor finishes higher.
End-of-day trailing drawdown example: the same trades, a different floor
An end-of-day trailing floor ignores intraday highs when those highs aren’t part of its update formula. It recognizes the qualifying closing balance instead. Under the same constructed trade path, the first session’s $600 closing gain raises the floor by $600 rather than the $1,200 open-equity gain.
Keep the $50,000 starting account and $1,500 allowance. This time, update the floor only at the session close, enforce it against equity throughout the session, and assume no lock. The account is flat at the first close.
| Moment | Equity or closing balance | EOD trailing floor | Room above floor |
|---|---|---|---|
| Start | $50,000 | $48,500 | $1,500 |
| Open trade reaches a $1,200 gain | $51,200 | $48,500 | $2,700 |
| Trade exits at $50,600, before session close | $50,600 | $48,500 | $2,100 |
| Session closes; floor updates | $50,600 | $49,100 | $1,500 |
| Next session: open loss of $1,000 | $49,600 | $49,100 | $500 |
The distinction happens at the close. Before the update, $50,600 is $2,100 above the old floor. After the update, the distance is back to $1,500. End-of-day trailing preserves intraday room temporarily; it doesn’t permanently turn every realized gain into extra cushion.
At the final checkpoint, the intraday model has already failed while the EOD model has $500 remaining. This comparison holds under the stated equal allowances, enforcement and no-lock assumptions. Different firm terms can change the outcome.
How does a static floor compare on the same path?
A static floor does not rise with profits. Using the same $48,500 initial floor, a $50,600 closing balance leaves $2,100 of room. The subsequent fall to $49,600 leaves $1,100. The difference comes from the rule’s reference point, not from a change in the strategy’s trades.
| Checkpoint | Equity | Static floor | Intraday equity-trailing floor | EOD trailing floor |
|---|---|---|---|---|
| Start | $50,000 | $48,500 | $48,500 | $48,500 |
| Open-equity peak | $51,200 | $48,500 | $49,700 | $48,500 |
| After first session closes | $50,600 | $48,500 | $49,700 | $49,100 |
| Next session’s low | $49,600 | $48,500 | $49,700: breached | $49,100 |
All values in these three examples are constructed illustrations, not measured trading results. No lock, payout, reset or other account adjustment is assumed. A breached attempt ends at its first violation.
Does end-of-day trailing mean losses are checked only at the close?
No. End-of-day can describe only the floor’s update schedule. A firm can hold that floor constant during the next session while continuously checking equity against it. An intraday dip can therefore violate the rule even if the account would have recovered by the close.
For example, Topstep’s Maximum Loss Limit documentation, checked on 16 October 2026, says its limit rises with end-of-day balances while enforcement includes realized and unrealized P&L during the session. A Trading Combine breach makes the account ineligible for funding until reset; the Express Funded Account has different consequences.
For a separate constructed example, suppose today’s enforced floor is $49,100. Equity falls to $49,050 before recovering to $50,200. Under a rule that prohibits touching or falling below the floor, the attempt failed during the dip. The later recovery cannot undo that violation.
When does trailing drawdown stop moving?
A trailing floor stops rising only when the account’s terms define a lock or cap. Once locked, future profits can increase the distance above that fixed floor. Before the lock, qualifying highs continue to raise the boundary. Account stages and payout events can change the rule.
Topstep’s documentation describes its Trading Combine floor locking at the starting balance. Its stated 50K Combine starts at $50,000 with a $2,000 allowance, so a qualifying $52,000 closing balance brings the floor to $50,000. Further profits no longer raise that locked floor.
Keep that named example separate from our earlier $1,500 no-lock model. It describes a specific product using the source’s current figures. Don’t transfer the same lock to another firm’s account or assume a funded-stage balance starts at the evaluation’s advertised size.
What should you check in a trailing drawdown backtest?
Check the account path against the correct floor at each enforcement point. A single maximum drawdown figure isn’t enough when its reference, sampling frequency or lock behavior differs from the firm’s rule. Your evidence should establish both the high that moved the floor and the low that tested it.
- Match the account. Record starting capital, allowance, product, stage and current rule source.
- Define qualifying highs. Specify live equity, realized balance or session-close balance.
- Define enforcement. Include open-position P&L and costs when the rule requires them.
- Set session boundaries. Use the specified closing time, timezone and daylight-saving treatment.
- Model locks and adjustments. Apply floor caps, payouts and resets according to the terms.
- Stop at the first breach. Later simulated profits cannot rescue that attempt.
- Review missing evidence. If the export cannot establish open equity, keep that part of compliance unresolved.
With overlapping positions, individual trade outcomes don’t provide the complete account path. You need their combined exposure over time. A recovered open loss and a temporary open gain can both matter even when every exported exit looks harmless.
How should you interpret Tradelyze’s trailing modes?
Tradelyze’s custom rule documentation distinguishes Trailing Realtime from Trailing EOD, but describes both as calculations built from closed trades. Trailing Realtime follows balance highs after trade exits; it does not capture every open-equity high. The documented trailing modes also do not lock at the starting balance.
That creates two separate modeling gaps. Missing open gains can keep a simulated floor too low, while missing open losses can hide a breach. Continuing to trail after a firm’s lock can make the later simulation stricter. These differences don’t reliably cancel each other out.
Match the chosen mode to the firm’s definition, then document what remains unverified. Set script starting capital to the intended account size before interpreting percentage limits. For the full workflow, see how Tradelyze validates a strategy.
Frequently asked questions
Yes, when the applicable floor has risen above the starting account value. In a constructed no-lock model, a $53,000 qualifying high and $1,500 allowance produce a $51,500 floor. Falling to that boundary can end eligibility despite a $1,500 gain from a $50,000 start.
Don’t assume it does. A daily loss limit and a trailing maximum loss rule are separate. A trailing floor generally retains its prior qualifying high unless the terms specify a reset or adjustment. A new session may update the floor without restoring yesterday’s lost room.
It may reduce intended trade risk, but it doesn’t lower a floor that has already risen. After a large open gain, even an exit near entry can leave the account close to an equity-based trailing limit. Execution slippage can also change the realized exit.
With identical allowances, continuous enforcement and no locks, an equity-based intraday model recognizes at least as high a peak as a closing-balance model. Its floor is therefore at least as high. Real account comparisons must also consider different allowances, locks, fees, restrictions and stages.
Test the floor your account actually uses
Before trusting a trailing drawdown result, write down the update rule, enforcement rule and lock rule. Then replay the strategy against those definitions. The relevant question is whether the account survived every enforced boundary, including the moments its final profit figure doesn’t show.
Use Tradelyze to review your strategy’s historical evidence, compare the documented drawdown assumptions with your intended account, and identify the open-equity checks that still need investigation.
Disclaimer:
This content is for informational purposes only and does not constitute financial, investment, or trading advice. Trading and investing in financial markets involve risk, and it is possible to lose some or all of your capital. Always perform your own research and consult with a licensed financial advisor before making any trading decisions. The mention of any proprietary trading firms, brokers, does not constitute an endorsement or partnership. Ensure you understand all terms, conditions, and compliance requirements of the firms and platforms you use.
Also Checkout: Prop Firm Backtesting: Rules and Metrics to Check
One Comment